4
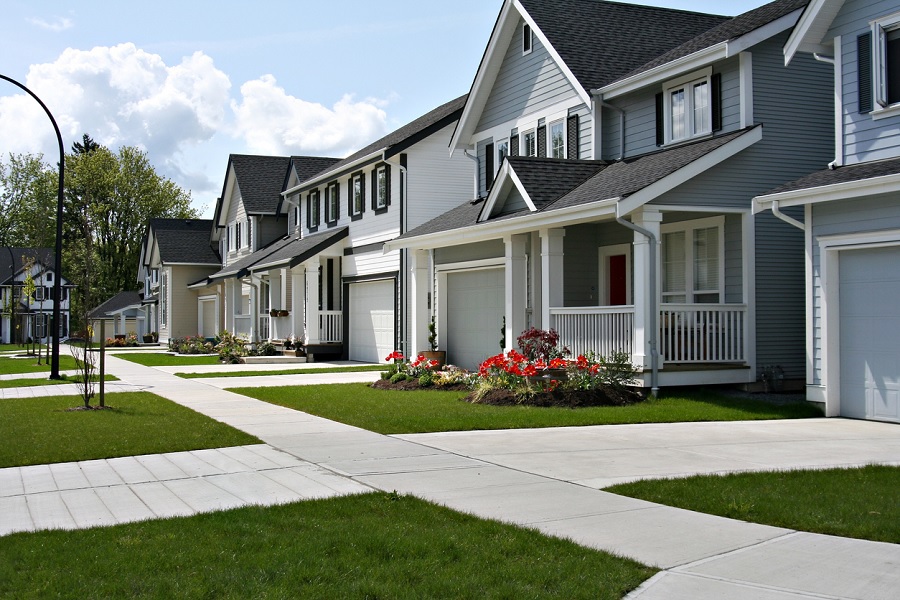
Finding the ideal suburban home often triggers a rush of classic real estate daydreams. You picture manicured lawns, quiet cul-de-sacs, safe neighborhood streets for evening walks, and a strong sense of community. For millions of American homebuyers, these idyllic suburban features come wrapped in a singular administrative package: the Homeowners Association. Today, a staggering percentage of newly constructed suburban properties and planned communities operate under the governance of an HOA. While these organizations promise to protect property values and maintain neighborhood aesthetics, they also introduce a parallel legal and financial system that every prospective buyer must navigate with open eyes.
Jumping into a suburban purchase without thoroughly investigating the local homeowners association is one of the most expensive risks a buyer can take. Beyond your mortgage, property taxes, and homeowners insurance, an HOA introduces mandatory monthly or annual dues, strict behavioral covenants, architectural oversight committees, and potential penalty structures. Understanding how these associations operate, what questions to ask, and how to read between the lines of their governing documents can mean the difference between a peaceful suburban sanctuary and a daily administrative battleground.
Unpacking the Financial Realities of HOA Dues
The most immediate financial impact of purchasing an HOA-governed property is the regular assessment fee. When you buy into a community, you are legally entering into a binding contract that requires you to contribute financially to the shared upkeep of the neighborhood. These fees can range anywhere from fifty dollars a month for a basic master-planned subdivision to several hundred or even thousands of dollars monthly for upscale communities featuring private gates, community pools, clubhouses, or extensive landscaping maintenance.
When reviewing the HOA budget, you must look far beyond the current monthly fee. Operating costs rise alongside inflation, labor costs, and municipal utility rates, meaning HOA fees almost always trend upward over time. More importantly, you need to examine the association balance sheet to evaluate its reserve fund health. The reserve fund is the community savings account dedicated to major capital repairs and replacements, such as repaving community roads, replacing clubhouse roofs, or upgrading common-area infrastructure.
If an HOA has chronically underfunded its reserves to keep monthly dues artificially low to attract buyers, you are walking into a financial trap. Underfunded reserves inevitably lead to special assessments. A special assessment is a sudden, mandatory lump-sum charge levied on every homeowner to cover unexpected major repairs or shortfalls. Discovering six months after moving in that you owe three thousand dollars for a new neighborhood drainage system can devastate your household budget. Always request a reserve study during your real estate transaction review period to ensure the community is financially sound.
Decoding the Covenants, Conditions, and Restrictions
While the financial obligations demand careful attention, the behavioral rules enforced by an HOA often dictate your day-to-day quality of life. These rules are codified in a lengthy legal document known as the Declaration of Covenants, Conditions, and Restrictions, commonly abbreviated as CC and Rs.
Many buyers make the mistake of skimming these documents or relying solely on the real estate agent summary, treating them as standard legal boilerplate. In reality, the CC and Rs represent the ultimate rulebook for your property. They govern everything from what color you can paint your front door to where you are allowed to park your vehicles.
Common Restriction Categories to Scrutinize
-
Architectural Oversight: If you plan to build a backyard deck, install a backyard shed, put up a solar array, or plant a specific type of garden, you will likely need architectural committee approval. This process can take weeks, and the committee holds the legal authority to reject your design choices entirely if they do not align with community aesthetics.
-
Vehicle and Parking Rules: Many suburban HOAs enforce strict overnight street parking bans. Some communities prohibit commercial vehicles, RVs, boats, or trailers from being parked in driveways, forcing owners to find off-site storage. If you own a work van or a recreational vehicle, failing to check these rules before buying can leave you with nowhere to park your own property.
-
Pet Policies: Do not assume a suburban home with a fenced yard automatically welcomes your pets. HOAs frequently enforce strict limitations regarding the number of pets, maximum weight limits for dogs, and outright bans on specific dog breeds deemed aggressive by the board.
The Dynamics of HOA Governance and Power
Beyond the written rules, the practical enforcement of an HOA depends entirely on the people sitting on the elected board of directors and the management company they hire. An HOA is, at its core, a micro-government. Board members are typically volunteer homeowners who hold the power to interpret rules, issue fines, initiate legal action, and manage community funds.
A well-run HOA maintains a professional, communicative, and balanced approach, enforcing rules reasonably while focusing on long-term property value preservation. However, an unorganized or overzealous board can create a hostile living environment. Some neighborhoods suffer from overly restrictive enforcement where board members issue fines for minor infractions, such as leaving trash cans out an hour past the designated collection window or parking slightly over the property line.
Before making an offer, try talking to a few current residents away from the official open house setting. Ask them about their experiences with the board, how quickly maintenance requests are handled, and whether fine enforcement feels fair or arbitrary. Understanding the community culture provides invaluable insight into whether you will enjoy living under that specific governance structure.
Your Due Diligence Checklist Before Closing
Navigating an HOA purchase requires adopting a proactive due diligence mindset. Most states mandate a legal review period during which the seller must provide you with the complete association document package upon contract ratification. Treat this document review with the same scrutiny you would apply to a home inspection report.
-
Review the Master Insurance Policy: Understand what the HOA insurance covers versus what your personal HO-3 or HO-6 homeowners insurance policy must cover. In some townhome or condominium communities, the master policy covers the exterior structure, while in single-family associations, you are entirely responsible for the physical structure of the home.
-
Examine Meeting Minutes: Request the minutes from the past twelve months of board meetings. These documents reveal simmering neighborhood disputes, upcoming maintenance projects, pending litigation against the association, or discussions regarding potential fee hikes that have not yet been formalized.
-
Check for Pending Litigation: Find out if the HOA is currently involved in lawsuits. Communities involved in construction defect litigation with developers can face extended periods of instability, restricted financing options for prospective buyers, and delayed maintenance.
Striking the Right Balance
Suburban living with an HOA offers undeniable perks, including well-maintained shared amenities, predictable neighborhood standards, and the peace of mind that comes with collaborative community management. However, buying into an association means trading a degree of absolute personal autonomy for shared community governance.
By looking past the initial curb appeal, thoroughly evaluating the financial health of the reserve fund, reading the governing documents with care, and understanding the local board culture, you can ensure that your suburban investment delivers comfort and stability rather than unexpected administrative stress. Taking the time to master the fine print before signing on the dotted line guarantees that your new home remains a sanctuary of your own choosing.
